2027 Communication Disorders Student Debt Report: Borrowing, Monthly Payments, and Repayment Risk
Audited and Verified:
Our Editorial and Data Verification Process
Research.com uses government datasets, official education statistics and primary institutional information to support its career and degree guides. Our review process checks factual accuracy, occupational definitions, source dates and the requirements associated with the credentials discussed.
How This Article Was Fact-Checked
Our editorial team verifies salary estimates, employment projections, education requirements and program information against original data providers and official organizations. Salary figures are checked against the relevant occupational definitions and reporting periods. Information about licensure, accreditation and required in-person training is reviewed separately.
Fact-checked and verified on:

Co-Founder and Chief Data Scientist

Reviewed by Rhea Paul, PhD
SLP Education & Research Expert
A communication disorders degree can lead toward speech-language pathology or audiology, but the borrowing decision starts well before professional school. An undergraduate balance may be followed by a required graduate or doctoral program, making the total cost harder to judge from one school's tuition page. This report explains what published debt data can - and cannot - tell you, how to estimate payments, and which program and loan choices deserve scrutiny. Use it to compare the full path to licensure, not just the price of your next semester.
Key Things You Should Know
- There is no single reliable national debt or delinquency figure for all communication disorders graduates; program-level borrowing figures describe specific groups of borrowers, not everyone entering the field.
- For a prospective speech-language pathologist, undergraduate debt must be considered alongside the cost of a qualifying master's program; audiology generally adds a clinical doctorate.
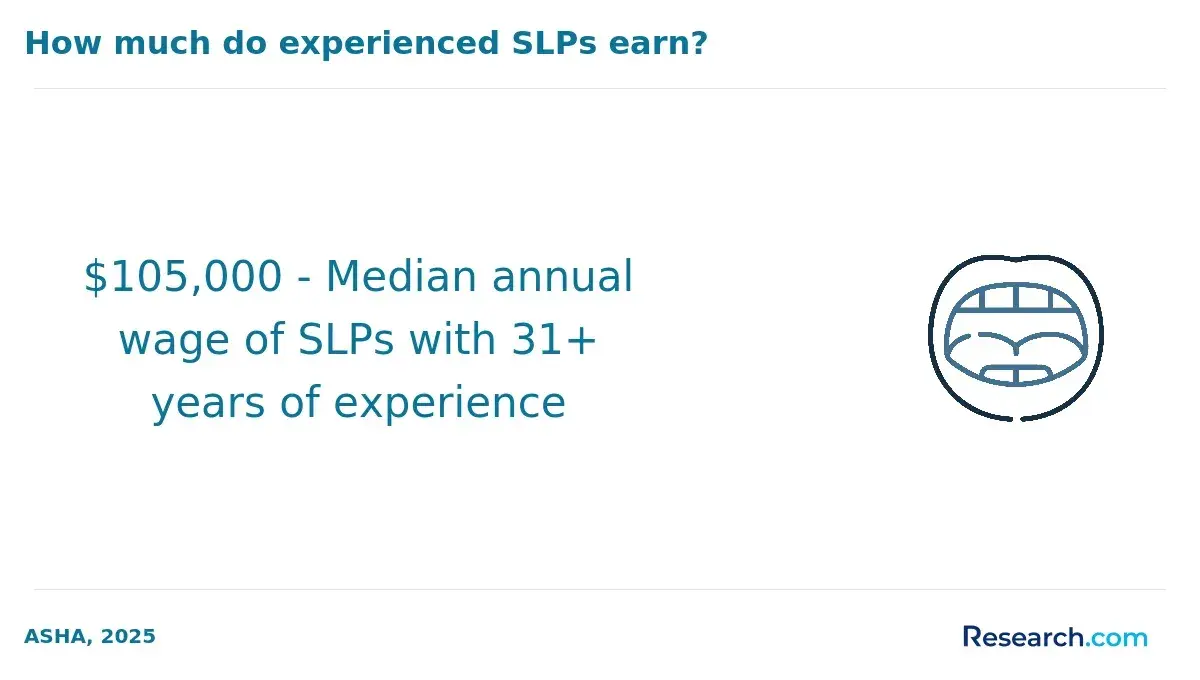
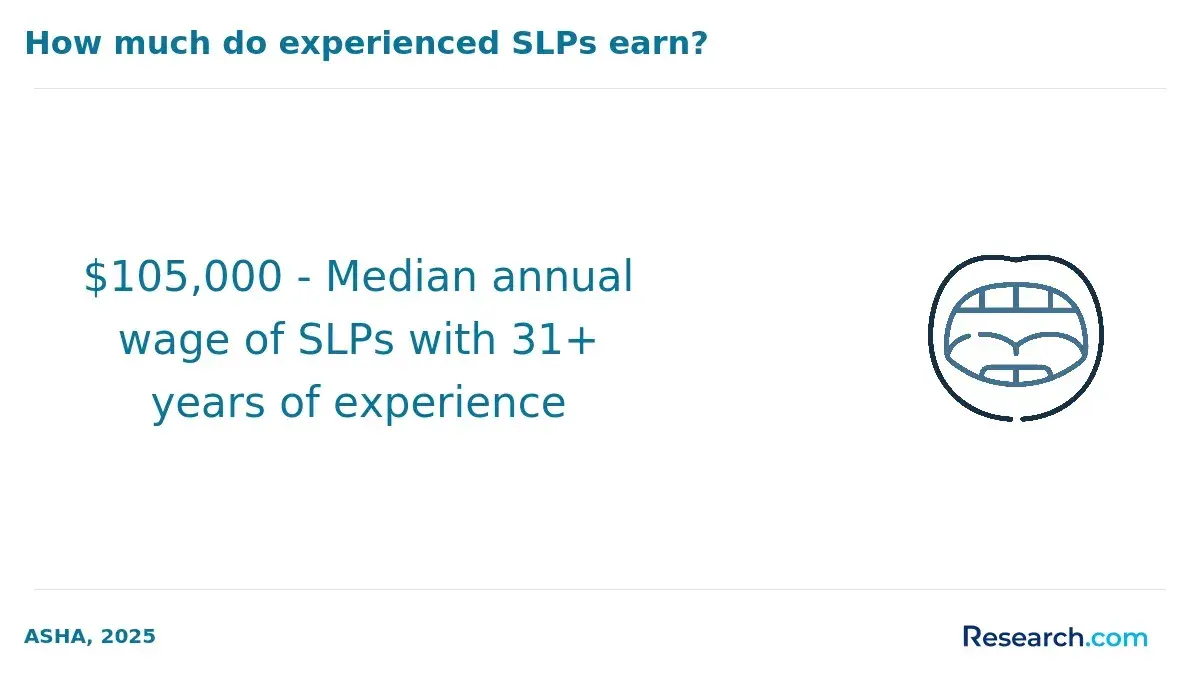
- The U.S. Bureau of Labor Statistics reports a $97,870 median annual wage for speech-language pathologists in May 2025. That occupation-wide figure is not a starting salary or a guarantee that a particular loan payment will be affordable.
- What does the current communication disorders student debt data show about borrowing and repayment risk? Borrowing Snapshot
- How much do communication disorders graduates borrow for undergraduate and graduate education? Total Borrowing
- What monthly student loan payments do communication disorders borrowers face after graduation? Monthly Payments
- Which communication disorders students face the highest risk of delinquency or default? Repayment Risk
- Which repayment plans, federal protections, and student aid decisions can reduce financial risk? Risk Reduction
What does the current communication disorders student debt data show about borrowing and repayment risk?
The most useful answer is program-specific: borrowing depends on which credential a student completes, whether they already have undergraduate loans, and how they finance clinical training. Public data do not establish one trustworthy debt median or default rate for everyone who studies communication disorders. A bachelor's graduate who enters the workforce and a licensed clinician who completed graduate school have different borrowing histories.
Published measures answer different questions. This table shows which comparisons are useful - and where a seemingly precise figure can mislead.
| Measure | What it can show | Key limitation |
| College Scorecard program debt | Typical reported debt for eligible borrowers who completed a particular program | Coverage, credential level, suppressed results, and included loans vary; it is not a field-wide total |
| School cost of attendance | Estimated tuition, fees, and living expenses for a stated enrollment period | It is a budget estimate, not the amount students borrow |
| Federal repayment or default data | Loan outcomes for defined borrower groups or institutions | Institution-level results should not be presented as a communication disorders major's default rate |
A low published program debt figure can reflect students who borrowed less, not necessarily a lower total price. Compare programs at the same credential level, check the population behind each figure, and treat missing or suppressed data as unknown - not zero.
How much do communication disorders graduates borrow for undergraduate and graduate education?
There is no defensible single borrowing amount for this field. A bachelor's degree in communication sciences and disorders may be a step toward graduate admission, but it generally does not by itself qualify someone to practice as a speech-language pathologist or audiologist. The relevant financial question is how much debt will remain after all required education, not just at undergraduate graduation.
Students entering an SLP master's program from another major may need prerequisite or leveling courses. Those courses can add costs before graduate tuition begins; compare choosing online SLP prerequisites for graduate school with each target program's actual admissions requirements rather than assuming every course will transfer.
Request a term-by-term estimate that separates tuition, mandatory fees, prerequisites, clinical placement expenses, travel, and living costs. Subtract grants and other funding that do not require repayment, then add any existing loan balance. That produces a more useful borrowing forecast than an advertised tuition rate.
What monthly student loan payments do communication disorders borrowers face after graduation?
A monthly payment cannot be determined from a major or degree title. Under a fixed-payment plan, it depends on the balance when repayment begins, the interest rates on individual loans, and the repayment term. Interest that accrues during school can make the repayment balance larger than the amount originally disbursed. Income-driven federal payments instead depend on the applicable plan's rules and the borrower's financial circumstances; a lower monthly bill may extend repayment or increase total interest.
To test affordability, enter each loan's projected repayment balance and interest rate into a federal loan simulator or servicer calculator. Compare the resulting standard-plan payment with a currently available income-driven option, and review both the monthly bill and projected total paid. Do not use a salary median as your expected take-home pay.
Speed can also change the calculation: intensive online speech pathology programs may reduce time away from full-time work, but a demanding course and clinical schedule may limit earnings while enrolled. Compare the full cost and feasible work hours, not program length alone.
Which communication disorders students face the highest risk of delinquency or default?
Published evidence does not justify assigning a major-specific delinquency or default rate to individual students. The clearest warning sign is a projected payment that exceeds what the borrower can sustain after housing, transportation, insurance, and other essentials. Risk can rise when a student leaves without the credential needed for their intended job, carries undergraduate loans into graduate school, relies on expensive private borrowing, or has irregular income after graduation.
Delinquency means a payment is past due; default is a later, more serious loan status governed by the loan's rules. Neither is inevitable when a borrower struggles. Before enrolling, stress-test the budget against a lower-than-hoped-for starting wage and a delayed start to paid clinical work. If repayment becomes difficult, contact the federal servicer or private lender before missing payments to review available options.
How do debt and repayment outcomes differ between speech language pathology and audiology students?
The paths should not be pooled into one debt comparison. Speech-language pathologists generally need a qualifying master's degree and state licensure; audiologists generally need a clinical doctorate and state licensure. Program length, clinical requirements, and opportunities to work during training can therefore differ, but degree title alone does not establish which graduate will borrow more.
This comparison identifies the credential and cost questions to resolve before using a school's reported debt figure.
| Path | Typical professional education | Debt comparison that matters |
| Speech-language pathology | Qualifying master's program after undergraduate study | Combined undergraduate, prerequisite, and master's borrowing |
| Audiology | Clinical audiology doctorate after undergraduate study | Combined undergraduate and doctoral borrowing, including clinical-training costs |
For SLP applicants who need leveling coursework or are weighing admission routes, SLP master's programs with flexible entry requirements can be a starting point for comparison. Verify each program's current prerequisites and costs directly; an easier entry route is not necessarily a cheaper route to licensure.
How do borrowing outcomes vary by degree level, institution type, and enrollment status?
Degree level changes the number of educational stages a student must finance. Institution type may affect tuition and aid, but public versus private status alone does not determine net cost, placement expenses, or earnings. A part-time schedule can spread tuition payments while extending living costs; full-time enrollment can shorten the timeline while reducing paid work hours.
Online study does not automatically eliminate travel or clinical costs. Compare the tuition actually charged to your state of residence, required campus visits, and who arranges placements. This is particularly important when evaluating out-of-state costs for online speech pathology degrees.
Ask each school for a total program estimate under your enrollment schedule. If one school quotes per-credit tuition and another quotes an annual amount, convert both to the full required course of study before deciding which is less expensive.
How do federal loan balances, private loans, and graduate borrowing affect repayment exposure?
Federal and private loans can create different risks even when their initial monthly payments look similar. Federal loans may offer income-driven repayment, certain deferment or forbearance options, and potential Public Service Loan Forgiveness eligibility. Private-loan terms depend on the contract and generally do not carry those federal protections. Graduate borrowing can add substantial repayment exposure to an existing undergraduate balance.
Loan availability and limits can change, so confirm the rules that apply to your borrowing date rather than relying on an older program budget. When comparing aid offers, distinguish grants and assistantship funding from loans, and distinguish federal loans from private credit. A private loan's advertised rate may also depend on creditworthiness or a cosigner.
A common mistake is treating the maximum amount offered as the amount needed. Build a term-by-term budget first, borrow only against the remaining gap, and keep a record of each loan's rate, balance, and repayment protections.
How do communication disorders debt outcomes compare with earnings and professional licensure pathways?
The Bureau of Labor Statistics reports that the median annual wage for speech-language pathologists was $97,870 in May 2025. That is the midpoint across employed workers in the occupation - not a forecast for a new graduate, an audiologist, or someone whose bachelor's degree does not qualify them to practice. BLS also projects 17% employment growth from 2025 to 2035 for speech-language pathologists; projected demand does not remove the need for a workable repayment budget.
Location and employer matter when comparing likely pay with debt. Information on the best-paying states for speech pathologists can help frame a search, but weigh any higher wage against local living costs and the jobs you can realistically pursue.
Before treating a program as an investment in licensed practice, confirm its current accreditation status and ask the relevant state licensing board whether the education and clinical pathway meets its requirements. For SLP master's programs, check status with the Council on Academic Accreditation. Neither admission nor graduation alone guarantees licensure or employment.
What methodology and borrower definitions produce the communication disorders debt estimates?
Debt figures are only comparable when they describe the same population and point in time. A program median may cover borrowers who completed a specified credential, while another figure may describe all graduates, federal-loan recipients, or borrowers at an entire institution. These are not interchangeable. Privacy suppression can also leave small programs without a published result.
For a sound comparison, identify the credential and program, the graduating cohort, whether the measure is a median or average, which borrowers and loan types it includes, and when the balance was measured. Check separately whether undergraduate and prior graduate debt are included. Public program debt data should not be relabeled as all-in lifetime borrowing, and institution-wide default data should not be relabeled as the default rate for speech-language pathology or audiology.
This report therefore does not publish an unverified field-wide borrowing, payment, delinquency, or default figure. Its payment guidance is a calculation framework, not a claim about a typical communication disorders borrower.
Which repayment plans, federal protections, and student aid decisions can reduce financial risk?
The strongest protection starts before borrowing: choose a program that meets the credential goal at a manageable total cost. Then compare the federal repayment options currently available to you. Income-driven plans can tie eligible federal-loan payments to income under their applicable rules; Public Service Loan Forgiveness may benefit borrowers who satisfy its loan, employer, repayment, and qualifying-payment requirements. Neither should be assumed without checking eligibility.
Use this sequence to turn an aid offer into a repayment decision:
- Verify accreditation, state licensure disclosures, clinical requirements, and the complete cost through graduation.
- Compare grants, employer support, assistantships, and feasible work income before choosing a loan amount.
- Estimate payments using all existing and proposed loans, then test the budget against a cautious starting-income scenario.
- Confirm current federal loan and repayment rules, and read private-loan terms before signing.
Do not assume a shorter online program automatically lowers risk. When reviewing short online SLP degrees and state licensure preparation, confirm clinical scheduling, travel, and state-specific requirements alongside the advertised timeline.
References:
- U.S. Bureau of Labor Statistics - Speech-Language Pathologists https://www.bls.gov/ooh/healthcare/speech-language-pathologists.htm
- ASHA EdFind - Accredited Speech-Language Pathology Programs https://find.asha.org/ed/
- ETS Praxis - Speech-Language Pathology (5331) https://praxis.ets.org/test/speech-language-pathology-5331.html
- New York University - Online MS, Communicative Sciences and Disorders (Speech@NYU) https://steinhardt.nyu.edu/degree/online-ms-communicative-sciences-and-disorders
- University of North Carolina at Greensboro - Speech-Language Pathology, M.A. (Online) https://csd.uncg.edu/graduate/masters-of-arts-online/
- Pennsylvania Western University - Master of Science in Speech-Language Pathology https://online.pennwest.edu/programs/speech-language-pathology-grad/index.php
- California State University-Northridge - Master of Science in Communicative Disorders (Online) https://tsengcollege.csun.edu/programs/CDS
- Nova Southeastern University - SLP Program - Master of Science in Speech-Language Pathology https://osteopathic.nova.edu/degrees/masters/speech-language-pathology/index.html
Other Things You Should Know About Speech Pathology
Not necessarily. Compare your loan rates, available savings, graduate aid, and ability to cover living costs. Keeping a cash reserve may be more useful than paying down a low-rate loan immediately before an expensive clinical program.
Graduate students in communication disorders can usually borrow Direct Unsubsidized Loans up to $20,500 per year, with a $138,500 aggregate limit that includes undergraduate borrowing. If costs exceed that amount, many students use Grad PLUS loans, which require no set credit score but do require a federal credit check.
Online delivery alone does not determine eligibility. Check the program's accreditation, clinical training, and disclosures for the state where you intend to practice, then confirm requirements with that state's licensing board.
It can be available to borrowers with eligible federal loans who meet program requirements while working for a qualifying employer, such as an eligible government or nonprofit organization. A job title or school-based role alone does not establish eligibility.